

Blog / Guide
GuideManufacturing Cost Reduction Strategies: Direct Material & Component Cost Savings

Cost It Right
Aug 12, 2026 • Updated
Listen to this article
AI narration • 14:19 listen
0:00 / 14:19
Why Manufacturing Cost Reduction Needs a Different Approach
Manufacturing cost reduction is the practice of permanently lowering the cost of producing a part, assembly, or product- through better material utilization, process efficiency, supplier negotiation, and commodity management- without compromising quality or delivery.
It needs to be treated as a distinct discipline from general procurement cost reduction, for a simple reason: most procurement cost-savings content focuses on indirect spend- travel, software licenses, facilities, professional services, and maverick spending controls. Those strategies matter, but they don't touch the largest cost category most manufacturers carry: direct materials and components, which commonly account for 50–70% of total manufacturing cost. A manufacturer can run a best-in-class indirect procurement program and still leave the majority of its cost-reduction opportunity untouched if direct material and component costs aren't addressed with the same rigor.
This guide focuses specifically on that gap- the strategies that reduce the cost of what actually goes into your product, not just what your organization spends around it.
Cost Reduction vs. Cost Avoidance vs. Should-Cost Analysis
Manufacturing and procurement teams often use these terms interchangeably, but they describe different things:
Term | What It Means | Example |
Cost Reduction | Permanently lowering the actual cost of a part or process | Improving material utilization to reduce steel consumption per part |
Reactive Cost Saving | A fast, often reactive reduction that may affect quality or service | Switching to a cheaper, unvetted supplier under budget pressure |
Cost Avoidance | Preventing a future cost increase rather than lowering a current cost | Locking a fixed-price contract before a commodity price rise |
Should-Cost Analysis | Building an independent, bottom-up model of what a part should cost, used as the basis for negotiation | Modeling a stamped bracket's material, labor, and MHR cost to benchmark against a supplier's quote |
Should-cost analysis is the piece most generic procurement cost-reduction guides skip entirely, because it's specific to manufacturing. It's also what makes every other strategy in this guide more effective- you can't reliably negotiate, consolidate, or renegotiate a supplier contract without first knowing what the part should actually cost.
Strategy Overview: Cost Reduction by Lever
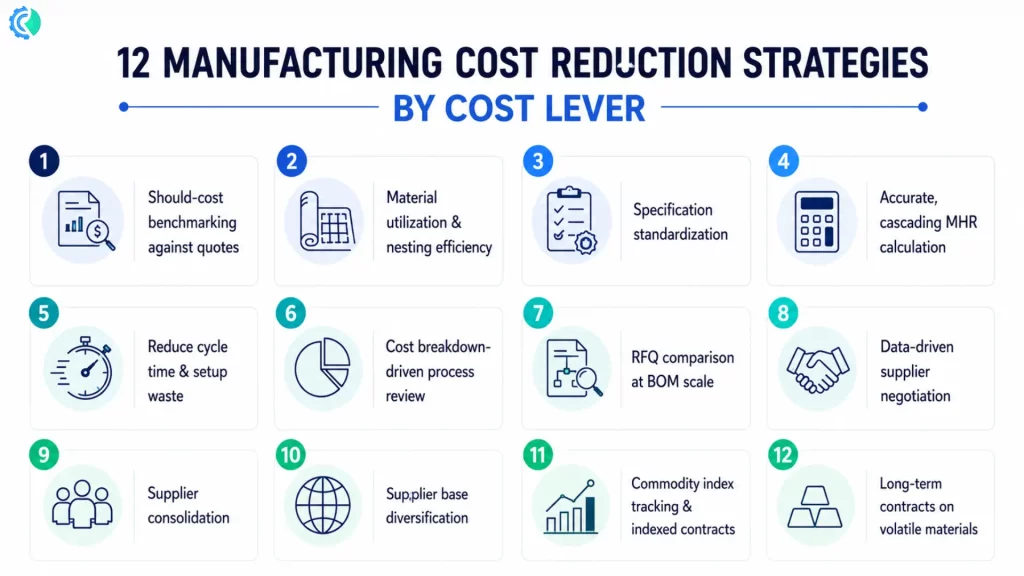
12 manufacturing cost reduction strategies by cost lever
Rather than organizing strategies purely by implementation timeline, this guide groups them by cost lever- the actual mechanism driving the cost- because that's how a costing engineer or procurement manager typically diagnoses where money is going. Timeline is noted for each as a secondary reference.
Strategy | Cost Lever | Typical Savings Timeline | Who Owns It |
Should-cost benchmarking against quotes | Direct Material | Short-term (weeks) | Costing / Procurement |
Material utilization & nesting efficiency | Direct Material | Short-to-medium term | Engineering / Costing |
Specification standardization | Direct Material | Medium-term | Engineering / Procurement |
Accurate, cascading MHR calculation | Process / Machine | Short-term | Costing |
Reduce cycle time & setup waste | Process / Machine | Medium-term | Manufacturing / Process Engineering |
Cost breakdown-driven process review | Process / Machine | Medium-term | Costing / Operations |
RFQ comparison at BOM scale | Supplier / RFQ | Short-term | Procurement |
Data-driven supplier negotiation | Supplier / RFQ | Short-term | Procurement |
Supplier consolidation | Supplier / RFQ | Medium-term | Procurement |
Supplier base diversification | Supplier / RFQ | Long-term | Procurement / Sourcing |
Commodity index tracking & indexed contracts | Commodity / Raw Material | Medium-to-long term | Procurement / Finance |
Long-term contracts on volatile materials | Commodity / Raw Material | Long-term | Procurement / Finance |
Direct Material Cost Reduction Strategies
Should-Cost Benchmarking Against Supplier Quotes:
Building an independent, bottom-up cost model for a part- based on material, labor, MHR, and overhead- gives procurement a defensible number to negotiate against, instead of accepting or rejecting a supplier's quote on instinct.
How to do this:Build a should-cost model for your highest-spend or highest-volume components first
Compare every incoming RFQ response against the model before it reaches approval
Flag and investigate any quote more than a set threshold above the should-cost figure
Improve Material Utilization and Nesting Efficiency:
Two suppliers quoting the same material grade can have meaningfully different true costs depending on how efficiently they nest or cut parts from raw stock. Material utilization is frequently a bigger cost lever than the underlying material price itself, particularly in sheet metal and machined components.
How to do this:Request nesting/utilization data from suppliers, not just per-part pricing
Compare utilization rates across suppliers quoting the same part
Work with engineering to adjust part geometry or blank size where utilization is poor
Standardize Specifications Across Components:
Component specifications are often set for a specific supplier, legacy design, or overly conservative tolerance- not the actual functional requirement. Standardizing specifications opens components to a wider, more competitive supplier pool and reduces the number of unique part variants a plant has to source and stock.
How to do this:Review specifications for parts with only one qualified supplier
Rewrite specs around functional performance rather than a specific brand or legacy design
Identify near-duplicate parts across product lines that could be consolidated into one standardized component
Process and Machine Cost Reduction Strategies (MHR-Driven)
Accurate, Cascading MHR Calculation:
Machine hour rate (MHR)- the combined machine, labor, and overhead cost per hour of a process- is the foundation of process cost accuracy. When MHR is outdated or calculated inconsistently across plants or suppliers, every cost estimate built on it is wrong by the same margin. Critically, when a machine or labor rate changes, that change needs to cascade automatically into every dependent cost- a manual, spreadsheet-based process makes this nearly impossible to maintain at scale.
How to do this:Recalculate MHR by machine and process at a fixed regular interval, not ad hoc
Ensure rate changes automatically update every dependent product cost
Benchmark your MHR figures against regional/process norms to catch outliers early
Reduce Cycle Time and Setup Waste:
For machining, stamping, and molding processes, cycle time and setup time are often larger cost drivers than the headline machine rate. Small, unaddressed inefficiencies compound across high-volume production runs.
How to do this:Identify components with unusually long cycle or setup times relative to similar parts
Work with process engineering to reduce non-value-added setup steps
Track cycle time as a cost variable, not just a throughput metric
Cost Breakdown-Driven Process Review:
Rather than reviewing cost reduction opportunities part by part, reviewing at the process level (all stamped parts, all machined parts, all molded parts) surfaces systemic cost drivers that a single-part view misses.
How to do this:Group components by manufacturing process and compare cost breakdowns across the group
Identify processes where your should-cost model consistently diverges most from supplier quotes
Prioritize process-level cost reduction efforts by total spend impact, not by part count
Supplier and RFQ Cost Reduction Strategies
RFQ Comparison at BOM Scale:
Comparing supplier RFQ responses one part at a time doesn't scale to a real bill of materials with hundreds of line items. Running RFQ comparison at BOM scale- against a should-cost benchmark for every line- surfaces the components with the largest quoted-vs-should-cost gap across an entire assembly at once.
How to do this:Run should-cost benchmarking across the full BOM, not just flagged high-spend items
Rank components by the size of the gap between quote and should-cost, not just by absolute spend
Prioritize negotiation effort on the highest-gap components first
Data-Driven Supplier Negotiation:
Negotiating from a should-cost breakdown- material, labor, MHR, overhead, margin- gives procurement a specific, line-item basis for discussion, rather than a single "please reduce your price" request.
How to do this:Share (or discuss) the cost breakdown categories driving the gap, not just the target number
Use historical RFQ and supplier performance data to support the negotiation position
Document negotiation outcomes against the should-cost baseline to refine future models
Supplier Consolidation for Volume Leverage:
Consolidating spend with fewer, stronger suppliers increases buying power and reduces the administrative overhead of managing a large, fragmented supplier base- as long as consolidation doesn't eliminate healthy competitive tension entirely.
How to do this:Identify components currently split across many low-volume suppliers
Benchmark consolidation candidates against should-cost data before committing volume
Maintain at least one qualified alternate supplier per critical component
Diversify Supplier Base to Reduce Single-Source Risk:
Over-reliance on a single supplier for a critical component is a cost risk as much as a supply risk- sole-source suppliers have little pricing pressure to stay competitive. Diversification protects both cost and continuity.
How to do this:Identify single-source components, especially high-spend or high-risk ones
Qualify a second source and benchmark their should-cost model against the incumbent
Rebalance volume gradually rather than switching suppliers abruptly
Commodity and Raw Material Cost Management
Commodity Index Tracking and Indexed Pricing Clauses:
Raw material prices- steel, aluminum, resins- move independently of any single supplier negotiation. Tracking commodity indices and building indexed pricing clauses into contracts keeps cost changes tied to actual market movement rather than a supplier's unilateral pricing decision.
This is one of the hardest steps to sustain manually, since commodity indices move continuously and every affected product cost needs to be re-checked whenever they do. Cost It Right's commodity indexing tracks these movements automatically and flags the specific products and contracts they affect, instead of requiring someone to notice the price movement and manually trace its downstream impact.
How to do this:Track relevant commodity indices for your top raw material spend categories
Build indexed pricing clauses into new and renewed supplier contracts
Flag existing contracts where commodity movement has created a should-cost gap
Long-Term Contracts and Strategic Hedging on Volatile Materials:
For materials experiencing sustained volatility or supply constraints, longer-term contracts and supplier diversification reduce exposure to short-term price spikes, even if they trade away some short-term negotiation flexibility.
How to do this:Identify materials with the highest recent price volatility in your BOM
Evaluate longer-term contract terms against current spot-market exposure
Diversify sourcing geography for critical volatile materials where feasible
Why Generic Procurement Software Misses Direct Material Costs
Most procurement cost-reduction platforms- spend analytics, purchase-to-pay automation, contract management tools- are built primarily for indirect spend: professional services, travel, facilities, software, MRO. They're genuinely effective at eliminating maverick spending, automating invoice processing, and centralizing supplier data.
But direct material and component costs work differently. They require a bottom-up, engineering-grounded cost model- material quantity, machine hour rate, labor time, tooling amortization- not a spend-pattern analysis. A platform built for indirect spend visibility generally can't tell you whether a stamped bracket's quoted price reflects the actual cost of steel, labor, and machine time that went into it.
That's the specific gap Cost It Right is built to close. Instead of treating should costing, RFQ analysis, MHR calculation, and commodity indexing as separate, disconnected activities, Cost It Right centralizes them in one platform built around manufacturing cost logic rather than general spend logic- so manufacturers with strong indirect procurement programs stop unknowingly overpaying on the direct material side, which is usually the larger opportunity.
How to Build a Manufacturing Cost Reduction Program
Start with should-cost benchmarking on your highest-spend components. You can't prioritize the rest of this list without knowing where the largest quote-vs-should-cost gaps actually are.
Fix MHR accuracy before negotiating. Every downstream cost estimate depends on it; negotiating from an inaccurate MHR baseline undermines the whole effort.
Run RFQ comparison at BOM scale, not part by part, to find where the biggest opportunities are hiding.
Layer in commodity tracking so raw material volatility doesn't silently erode gains from steps 1–3.
Centralize all of this in one system. Manufacturers doing this in disconnected spreadsheets typically lose the gains to manual rework, missed cascading updates, and inconsistent MHR figures across plants.
Cost It Right was built specifically to run all five of these steps in one connected workflow- should-cost modeling, MHR calculation with cascading updates, BOM-scale RFQ comparison, and commodity indexing- so a rate change, a new quote, or a material price shift updates every affected product cost automatically instead of requiring manual rework across disconnected spreadsheets.
FAQs
What are the most effective cost reduction strategies in manufacturing?
The highest-impact strategies are should-cost benchmarking against supplier quotes, accurate and cascading machine hour rate (MHR) calculation, RFQ comparison at full BOM scale, and commodity index tracking- because they address direct material and process costs, which typically represent the largest share of total manufacturing cost.
What are the cost reduction strategies in procurement generally?
General procurement cost reduction strategies include eliminating maverick spending, renegotiating supplier contracts, consolidating purchases, implementing category management, and adopting procurement technology. These primarily target indirect spend; manufacturers should pair them with direct-material-specific strategies like should-cost analysis for full coverage.
What is the difference between cost reduction and cost avoidance in manufacturing?
Cost reduction permanently lowers the actual cost of a part or process, such as improving material utilization. Cost avoidance prevents a future cost increase, such as locking a fixed-price contract before a commodity price rise. Both are valuable, but they show up differently- cost reduction is measurable against a prior baseline, while cost avoidance is measured against a cost that didn't happen.
How is should-cost analysis different from general cost reduction?
Should-cost analysis is a specific method: building an independent, bottom-up cost model of what a part should cost, based on material, labor, machine, and overhead data. It's the analytical foundation that makes negotiation-based cost reduction strategies effective, because it gives procurement a defensible benchmark rather than an intuition-based target.
What are strategic procurement strategies for manufacturers specifically?
Beyond general strategic sourcing, manufacturers benefit most from strategies grounded in engineering and cost data: should-cost benchmarking, MHR-driven process costing, BOM-level RFQ comparison, and commodity indexing- strategies that address direct material and component costs rather than only indirect spend.
How much of manufacturing cost is typically direct material?
Direct materials commonly represent 50–70% of total manufacturing cost, depending on the industry and process, making them the single largest cost-reduction lever available to most manufacturers- larger than labor, overhead, or indirect spend in most discrete manufacturing contexts.
Related Articles
Jun 15, 2026 • 9 min read
Why Material Utilization Matters More Than Material Price
Most OEMs focus on steel prices, but material utilization often has a bigger impact on sheet metal component costs. Learn how scrap, nesting, and yield affect profitability.
Jun 10, 2026 • 9 min read
The Hidden Cost Drivers in Sheet Metal Components That OEMs Often Miss
Sheet metal component costs are influenced by more than just material prices and supplier margins. Discover the hidden cost drivers affecting manufacturing costs, supplier quotations, and OEM profitability, including material utilization, scrap generation, tooling complexity, secondary operations, and quality requirements.
Oct 8, 2025 • 5 min read
How Procurement Cost Analysis Reduces Expenses
Struggling with shrinking margins? See how budgeting software brings clarity, control, and profit back.